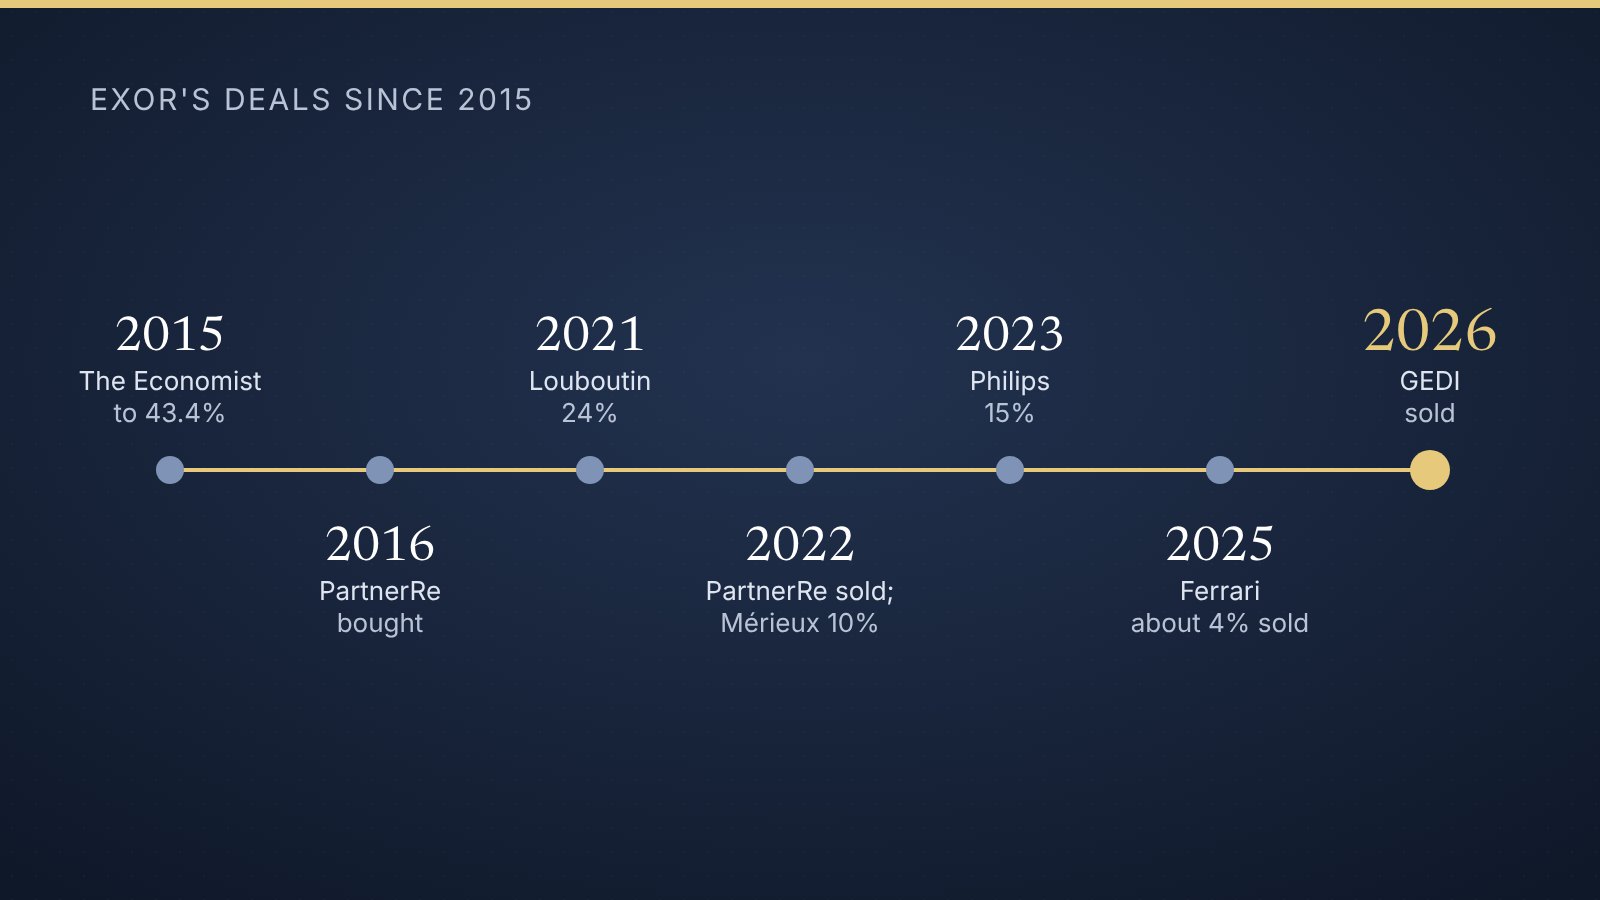
Exor, the Amsterdam-listed holding company controlled by the Agnelli family through Giovanni Agnelli B.V., has been both a buyer and a seller over the past decade. This post follows its main deals and what they show about minority stakes and the discipline to sell. Part 3 covered how the industrial group was split up; our Exor profile lists the current portfolio.
How Exor Won and Sold PartnerRe
The reinsurer PartnerRe had agreed to combine with AXIS Capital Holdings when Exor made a competing bid in April 2015, Artemis reported. Exor improved its terms several times, adding a completion guarantee. On 3 August 2015 PartnerRe dropped AXIS, paying it a $315 million termination fee, according to Artemis, and accepted Exor’s offer of $137.50 a share in cash plus a $3 special dividend, about $6.9 billion for the common shares. The deal closed in 2016, Exor’s history page says.
The exit took two attempts. A first agreement to sell PartnerRe to the insurance group Covéa fell through in 2020, during the pandemic, Insurance Business reported. A revived deal was signed in December 2021 at $9 billion in cash. On 12 July 2022 Exor completed the sale for a total cash consideration of $9.3 billion (about €8.6 billion), including a price adjustment partly paid as a March 2022 special dividend.
Minority Stakes, With a Seat at the Table
Exor often buys a minority stake and a voice, not control:
- The Economist Group. In August 2015 Exor agreed to pay Pearson £287 million for shares that, with a buyback of Pearson’s remaining shares, lifted its stake from 4.7% to 43.4% of the share capital. The articles were to cap any one shareholder’s votes at 20%. Fellow shareholders included the Cadbury, Layton, Rothschild and Schroder families.
- Christian Louboutin. Exor paid €541 million for 24% of the shoemaker, closing on 13 April 2021. It was to name two of seven board members, Modaes reported.
- Institut Mérieux. On 1 July 2022 Exor agreed to invest €833 million in new shares for 10% of the Mérieux family’s private healthcare holding, paid in instalments, with two seats on its board. Alexandre Mérieux said the support would allow more investment in its businesses “while preserving their independence”.
- Philips. Exor bought 15% in 2023 for €2.8 billion, its history page says, and held 18.9% of the economic rights at 30 June 2026. On 11 August 2026 Philips agreed to let it rise to 22% of shares and votes, from a 20% cap; Exor keeps the right to nominate one Supervisory Board member.
What Exor Sold in 2025 and 2026
- Part of Ferrari. In February and March 2025 Exor sold about 7 million Ferrari shares, about 4% of the company, for €3 billion, to reduce concentration and fund a new acquisition and a €1 billion buyback. Its economic stake fell from 24.9% to about 20%, and it stayed the largest shareholder.
- GEDI. In December 2019 Exor agreed to buy CIR’s 43.78% control stake in the publisher for about €102.5 million, with a mandatory offer for the rest to follow. In March 2026 it completed the sale of GEDI, owner of la Repubblica, to Antenna Group of Greece’s Kyriakou family, La Sicilia reported.
- Iveco Group. After Iveco sold its defence business to Leonardo, Exor received a €427 million extraordinary dividend. Tata Motors has offered €14.1 a share for Iveco, and Exor irrevocably committed to tender its 27.06% stake (43.19% of the votes), Autocar Professional reported on 5 September 2026. Exor expects closing in November.
- Welltec. In September 2026 Exor agreed to sell its stake in Welltec, a Danish maker of robotic tools for oil wells, at about 2.4 times the money invested, with closing expected in the first quarter of 2027.
A fair caveat
The Welltec price was not disclosed in the sources we read. Exor’s half-year report shows €119 million from the GEDI sale and a €130 million GEDI loan repayment. The PartnerRe figures include dividends and adjustments, so a simple return cannot be worked out from them. The Iveco sale was not yet final when we wrote this, on 27 October 2026.
Five lessons to take away
- Contests are won on terms, not price alone. Exor’s PartnerRe offer added a completion guarantee to a higher price.
- A minority stake can still bring a voice. Board seats at Louboutin, Mérieux and Philips came with stakes of 24% or less.
- Write the limits down. The Economist’s 20% voting cap and Philips’s 22% ceiling were agreed in advance.
- Trim without giving up the lead. Exor sold about 4% of Ferrari and stayed its largest shareholder.
- Selling is part of the strategy. A first exit can fail before a second succeeds, as PartnerRe showed.
For a family office
A family that invests beside another family can ask: what voice comes with a minority stake, and is it written down? What would make us sell, and who decides? How will we measure the result of an exit? These are questions to bring to your advisors, not advice.
