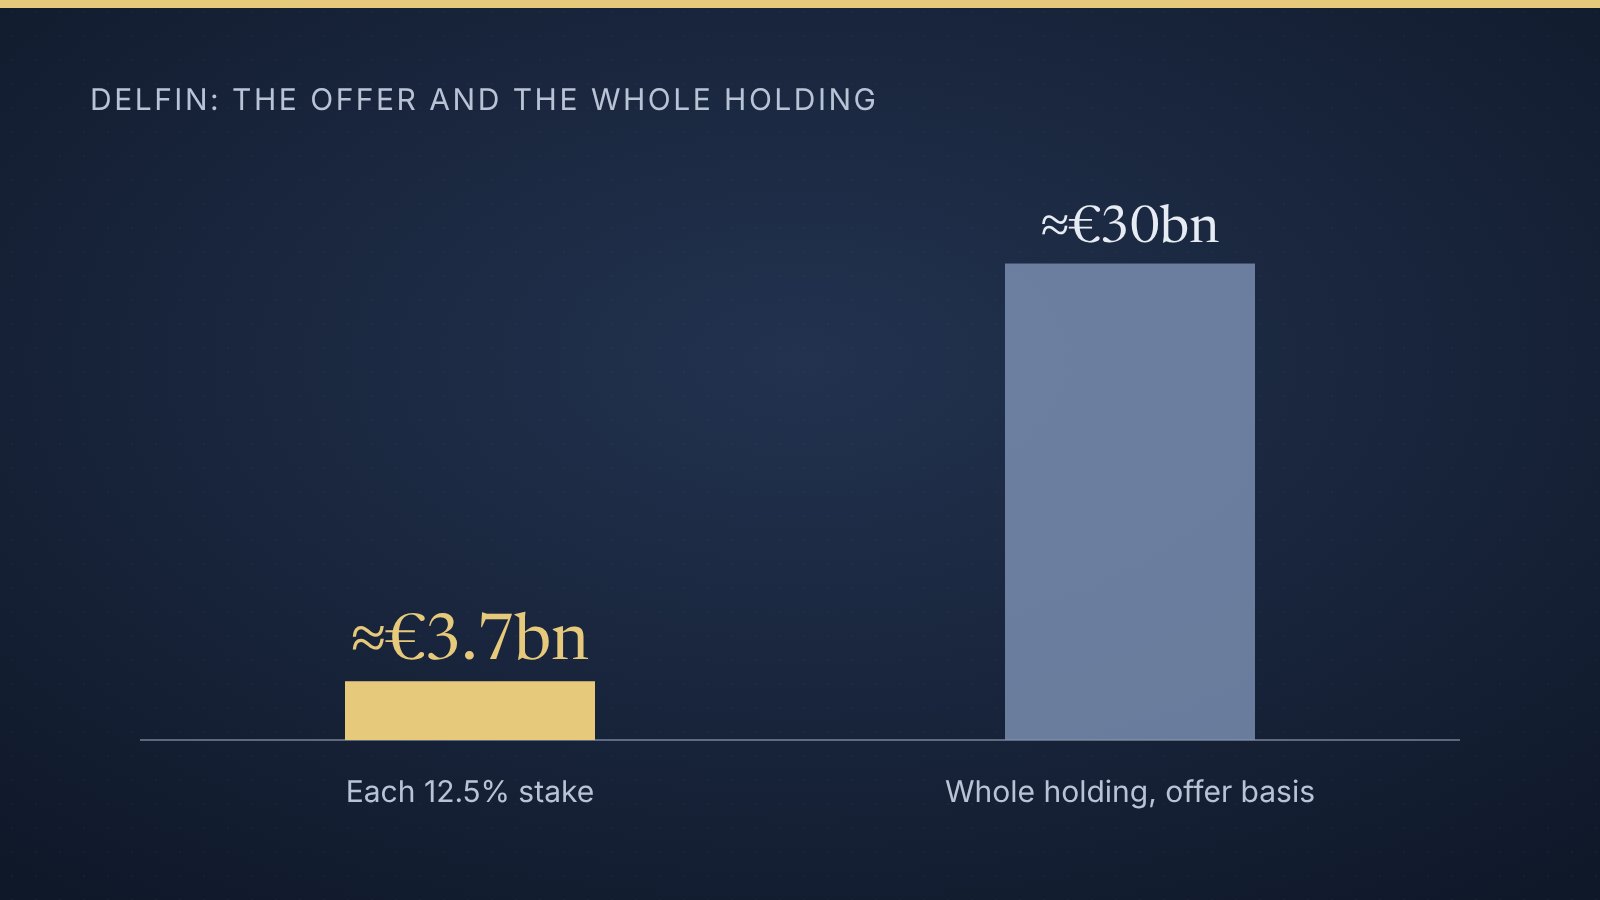
On 2 November 2026 Leonardo Maria Del Vecchio offered to buy out his relatives in Delfin, the Luxembourg holding company that owns 32.4% of EssilorLuxottica, at about €3.7bn for each 12.5% stake. That evening four of the eight shareholders said they would not sell, according to ANSA.
The bid shows how a stake in a family holding is priced and how bylaws let a minority block any buyer.
What Leonardo Maria Del Vecchio Offered
The terms of his letter, as reported by Milano Finanza (MF), Il Giornale and Quotidiano Nazionale:
- Target: the six stakes not held by him or his mother, Nicoletta Zampillo, taking him from 12.5% to between 62.5% and 87.5%.
- Price: Delfin’s net asset value (NAV) at market prices, less 30%, or about €30bn for the whole holding. Eight stakes at €3.7bn make €29.6bn (our calculation).
- Money: Citigroup said in a “highly confident letter” that it could arrange up to €22bn, not a binding commitment (MF).
- Payment: all cash, or 30% now and the rest after 12 to 14 months in EssilorLuxottica shares, at future NAV less 30%.
- Process: 30 days to accept, then 60 days of exclusivity. He asked to meet shareholders by 7 November (ANSA).
Who Said No, and the Arithmetic
Paola, Luca and Clemente Del Vecchio and Rocco Basilico said no, as they had to Michal Strnad’s earlier offer.
Our calculation: the four hold 50%. Without them, Leonardo Maria can reach at most 50%, and only by counting his mother’s stake, which his plan leaves out. That is short of his 62.5% floor and of the 75% that, MF says, he would need to change Delfin’s dividend policy and use its cash to repay the debt.
Strnad’s Earlier €30bn Offer
In a letter dated 20 October, Michal Strnad, owner of the Czech defence group CSG, offered €30bn in cash for the whole holding, valid for 30 days (Bloomberg). It depends on changing Delfin’s statute, which needs 88% of the votes. Both bids use NAV less 30%; Exor’s scorecard shows how wide holding discounts can be.
How Delfin’s Voting Rules Decide
As MF and Il Giornale report, a transfer to an existing shareholder needs more than two-thirds of the votes, and an outsider’s entry more than 88%. With eight 12.5% stakes, six clear two-thirds, but only all eight clear 88%. Holding half the votes, the four can block both routes. See also why the 88% rule binds Delfin’s heirs and how holding companies work.
Separately, Luca and Paola Del Vecchio claim a €500m penalty from Leonardo Maria in an arbitration over his failed June purchase of their stakes, according to MF. No ruling has been made.
A fair caveat
The terms come from press accounts and differ in detail. NAV, and so every price here, moves with EssilorLuxottica’s share price.
What to watch
- Whether anyone meets him by 7 November, and how Claudio and Marisa Del Vecchio respond.
- Strnad’s offer, which by our count lapses around 19 November unless extended.
- The end of March 2027, when a court-extended pre-emption period on several stakes ends.
Questions to bring to your advisors
If one of us bid for the others’ shares, what majority would approve it, and who could block it? How would we set a fair discount to NAV? These are questions to bring to your advisors, not advice.
