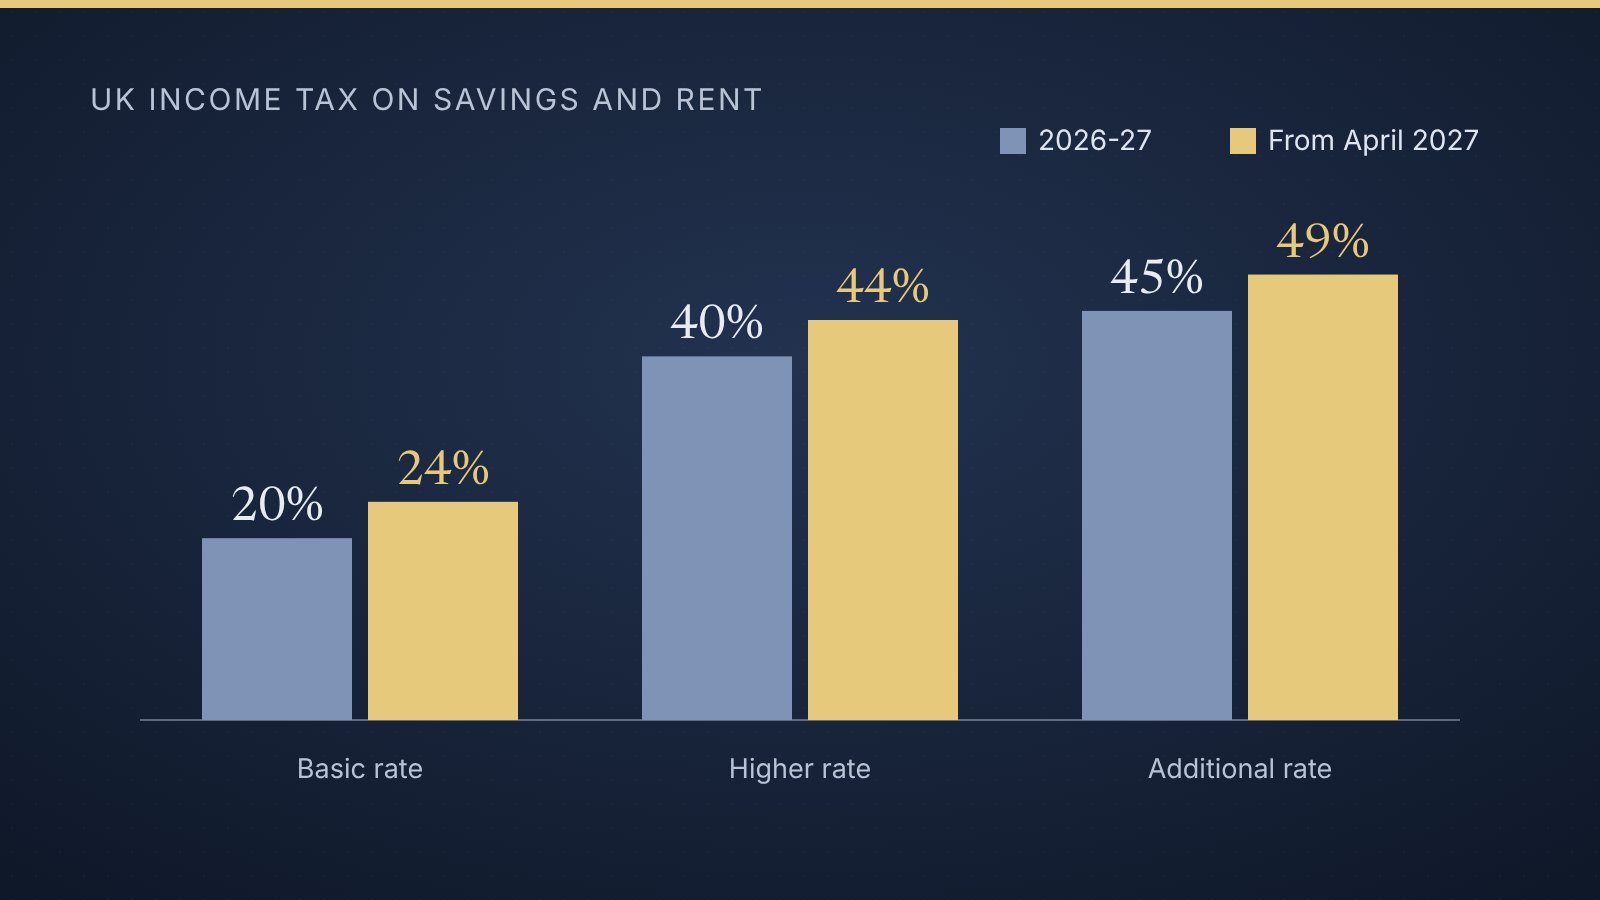
The UK Budget of 28 October 2026 left inheritance tax rates and thresholds unchanged, but it tightened one rule: from Budget day, certain debts inside trusts can no longer reduce the tax. Income tax on savings interest and on rent outside Scotland is due to rise to 24%, 44% and 49% from 6 April 2027, against 20%, 40% and 45% today. For families, the target is income from assets, not wages.
Inheritance Tax: Same Rates, One New Trust Rule
HMRC’s rates annex lists the same figures for 2026-27 and 2027-28: a 40% rate, a £325,000 nil-rate band and a £175,000 residence nil-rate band, withdrawn gradually above estates of £2m. They were already frozen until April 2031. The £2.5m allowance for 100% relief on business and farm property is unchanged.
The new rule is paragraph 1.26 of the Overview of Tax Legislation and Rates (OOTLAR). When trust property is valued, debts that trustees properly take on will count like an individual’s debts, while certain debts funded from a beneficiary’s own estate will not reduce the tax. It applies to deaths and other chargeable events from 28 October 2026, before Parliament has voted on it. Paragraph 1.27 makes technical changes to a rule already in law: most unused pension funds enter estates from 6 April 2027.
Savings and Rent: Four Points in Two Budgets
Budget 2025 had already set rates of 22%, 42% and 47% on savings and property income from April 2027, written into Finance Act 2026. This Budget adds two more points from the same date.
| Income | 2026-27 | Planned before this Budget | From 6 April 2027 |
|---|---|---|---|
| Savings interest | 20%, 40%, 45% | 22%, 42%, 47% | 24%, 44%, 49% |
| Rent (outside Scotland) | 20%, 40%, 45% | 22%, 42%, 47% | 24%, 44%, 49% |
| Wages (outside Scotland) | 20%, 40%, 45% | 20%, 40%, 45% | 20%, 40%, 45% |
Savings rates apply UK-wide; the Scottish Parliament and the Senedd can set their own property rates. Dividend rates and the £20,000 cash ISA limit stay. The Treasury says 84% of income tax payers will be unaffected. More detail: the new rates for landlords and tax on savings interest.
What It Means for a Family’s Mix of Income
The same wealth is now taxed differently depending on the income it produces: deposits and let property cost more from April 2027, dividends do not. OOTLAR does not change the residence-based inheritance tax rules for foreign families, explained in our check of the billionaire exodus claim and our UK guide.
What to watch
- The Finance Bill 2026-27, which must enact the new rates and the trust debt rule.
- Whether Scotland or Wales set their own property rates for 2027-28.
- HMRC guidance on which trust debts the draft law of 28 October catches.
A fair caveat
The rates are announced, not law, and can change in Parliament. HMRC’s policy paper on the trust rule gives no example or count of trusts affected.
Questions to bring to your advisors
How much of our UK income is interest or rent, and how much is dividends? Do any of our trusts carry debts? These are questions to bring to your lawyers and tax advisors, not advice.
